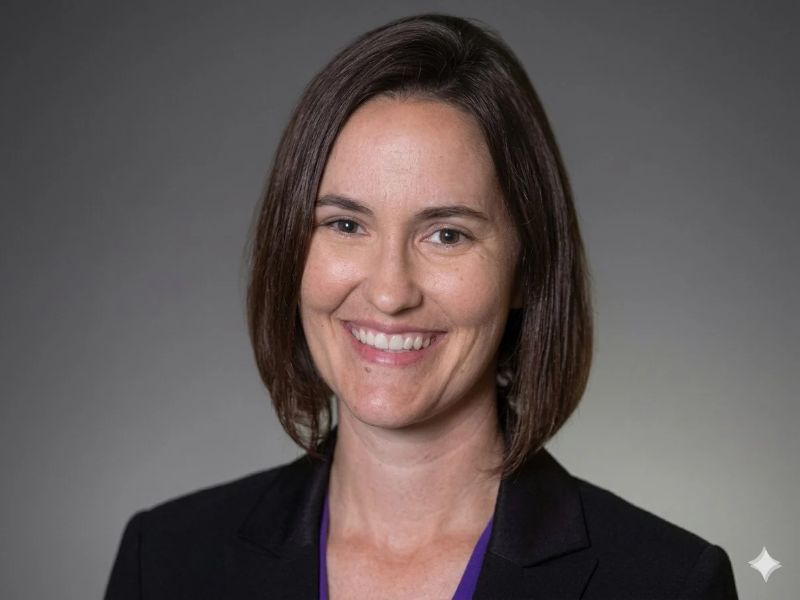
By Beth Crouchet, Director of Energy Markets, Virtual Power Plants
Climate Change Business Journal (CCBJ) is currently working on a special 2026 Renewable Energy Markets Edition. The edition will include articles, profiles or expert Q&As with selected companies.
These articles should not be seen as a venue for promotional writing about your company. Instead, we ask that you view your company and its challenges in the context of your segment, your region or the climate change industry at large.
Following is a list of questions and I ask you to answer only those you are comfortable with. I also encourage you to address whatever issues you consider to be of importance to your company and to the industry, so in that context, please feel free to 'insert' a question or two or to edit the questions on the list to fit your response.
Questions for CCBJ's Edition
Respondent: Beth Crouchet, Director of Energy Markets & Virtual Power Plants
Bio: Beth Crouchet is Director of Energy Markets & Virtual Power Plants at Budderfly, where she leads the company’s work in dynamic energy systems, including virtual power plants (VPPs) and battery storage deployments for small and mid-sized commercial customers. She led the team that launched some of the first VPPs in the country and is a 2025 TIME Magazine Award-winning inventor.
With almost a decade in the energy industry, Beth focuses on the small commercial sector, an underserved market, using energy efficiency, load flexibility, and net zero initiatives that can scale. Her background spans utility and product roles: she previously led utility solutions and product management at Resideo and ran demand response and new product research at Austin Energy.
Beth holds a master’s degree in Population and Conservation Biology from Texas State University and a BS in Environmental Science from Concordia University Texas. Her research on climate change and tree mortality was published in Frontiers in Forests and Global Change. She is based in Austin, Texas, and is a frequent public speaker on distributed energy and grid flexibility.
1) Include a brief description of your organization to serve as an introduction. Please provide approximate size of business (revenues and/or employees), recent growth, regional footprint, services offered, basic customer mix, etc. and the title, and short bio of respondents.
Budderfly is an energy-as-a-service company focused on serving small and mid-sized commercial buildings. We were founded in 2017 and are headquartered in Shelton, Connecticut. We provide the capital to upgrade a building’s energy infrastructure, including high-efficiency HVAC, lighting, refrigeration, controls, solar and batteries. We own and maintain that equipment, and we recover our investment through the energy savings it produces.
Today we manage more than 9,000 customer sites across 250+ brands in all 50 states, supported by 45 in-house technicians and more than 200 contractor and installer partners across 23 regions.
Our customers are commercial buildings including restaurants, fitness centers, retail locations, and manufacturing facilities with recent expansions into hospitality and municipalities. We have invested more than $378 million in customer facility upgrades to date and continue to drive down energy consumption across our customers with new innovative solutions.
We have also grown quickly. Budderfly has over 500 employees. Budderfly has been named to the Inc. 5000 list of America’s fastest-growing private companies for six consecutive years and to the Deloitte Technology Fast 500 from 2023 to 2025. Budderfly has grown 40-50% over the past few years and an annual recurring revenue above $350 million.
2) How would you characterize the U.S. Energy-as-a-Service market today? What is driving its growth, and how has the market evolved from traditional energy efficiency contracting and equipment financing toward more comprehensive energy management solutions?
The U.S. energy-as-a-service market has historically been built around large-scale projects for large institutional and public-sector customers. That leaves most small and mid-sized commercial buildings left behind — a huge, missed opportunity. The EPA and DOE estimate that 30% of the energy used in commercial buildings on average goes to waste. But an operator of a restaurant, gym, or small office rarely has the capital, the time or the in-house expertise to do the kind of complex procurement, construction, and ongoing maintenance and optimization that a successful energy efficiency strategy demands.
Three forces are pushing this segment to act. The first is price. Per the EIA, commercial electricity prices have risen 26% since 2021, increasing in 48 of 51 states. Small businesses are getting squeezed. For an operator with thin margins, that quickly turns from an annoyance into a real threat. The second is demand. EIA expects commercial electricity consumption to surpass residential consumption for the first time in 2027, in part because the commercial category includes data centers, which adds strain to the grid and makes efficient, flexible buildings more valuable. The third is labor. Skilled technicians are scarce, and small building owners rarely have maintenance teams of their own.
For all of these reasons, the market has been moving from one-time projects toward ongoing service. An owner who wants to fix that faces dozens of possible solutions to consider and no easy way to know where to start. The market simply was not built for them. That’s where we come in. We treat energy as a managed service across a business’ entire energy infrastructure and portfolio: we fund the upgrades, monitor performance with data, and invest in the long-term performance of the whole system.
We apply a mix of proprietary technologies and equipment upgrades for HVAC, refrigeration, lighting, storage, solar and more to keep driving that usage down and, in that sense, monetize the energy waste. After installation, we continue pushing toward greater demand-side efficiency, and that now includes load flexibility, demand response, and storage – all of which improve affordability and performance for the grid and for our customers.
3) Energy-as-a-Service is increasingly discussed as an alternative to conventional energy infrastructure ownership. What are the principal EaaS business models operating in the market today, and how do they differ in terms of financing, asset ownership, customer contracts, operational responsibilities, and risk allocation?
Energy-as-a-service is an umbrella term, and the models under it differ mainly in three ways: who pays up front, who owns the equipment, and who is left holding the risk if the savings do not show up.
While distinct from Energy-as-a-Service (EaaS), the most familiar legacy model is performance contracting, where an energy service company (ESCO) designs and installs a project and guarantees a specific amount of savings. Crucially, under a traditional performance contract, the customer finances the work through a lease or municipal financing, meaning the equipment sits directly on the customer’s balance sheet upon installation. While the ESCO backs the savings guarantee with a shortfall check if the system underperforms, the customer remains legally responsible for the underlying debt and retains the burden of day-to-day operations. Traditional equipment leases and vendor financing are at the simplest, non-service end of this spectrum: the customer or a third-party lessor owns the physical asset, while virtually all operational and performance risk stays entirely with the customer.
A second group consists of third-party-owned assets, such as solar Power Purchase Agreements (PPAs) and energy storage agreements. In these setups, the provider finances, owns, and operates a single asset under a long-term, single-asset contract and is paid either per kilowatt-hour or via a fixed capacity fee. Consequently, the provider carries the production risk for that specific asset, while the customer remains fully responsible for the energy efficiency and operations of the rest of the building.
Even within EaaS, the structures vary. In large health-system deals, for example, the provider designs, builds and operates the upgrades under a 30-year agreement with guaranteed savings, while the customer keeps ownership of the upgraded assets. Budderfly’s model is a whole-building managed approach. We finance the upgrades, own the energy infrastructure behind the meter, and become the customer of record for the utility bill. The customer pays a fixed monthly usage baseline, from 12 to 24 months of historical usage, minus a small discount, and we pay the utility. Because we pay ourselves in the energy savings generated, we carry the performance risk: if we do not reduce consumption, we do not recoup our investment. Once we do, we share the ongoing savings 50/50 with the customer. The agreement typically runs 10 to 15 years.
The practical difference is that in the other models the customer is still financing, owning or managing something. In ours the customer is not financing or managing a capital project at all, and their relationship is with us rather than with a patchwork of contractors. We wrote our own billing software to make this possible, because we want the customer’s experience to be as simple as possible.
4) Which commercial sectors are adopting Energy-as-a-Service most rapidly? Are restaurants, hospitality, retail, fitness centers, healthcare facilities, or other businesses emerging as particularly strong markets?
What these customers have in common is not the industry. It is thin margins, aging HVAC and refrigeration, and many similar locations, which lets us standardize a design and repeat it — a “rinse and repeat” approach. The same playbook that works across hundreds of restaurant locations works for a city’s facilities, because the underlying problem, aging equipment and tight budgets, is the same.
The strongest fit is multi-site operators with repeatable footprints. Restaurants and quick-service operators and fitness centers are core markets for us, and we are growing quickly in retail, hospitality and manufacturing.
We are now expanding into municipalities, as well. We announced a $500 million commitment of project capital, called Modernizing American Cities, to help small and mid-sized U.S. municipalities modernize their energy infrastructure without taking on debt or drawing on their capital budgets. We are teaming with Schneider Electric on the program. Our first municipality is the City of Cadillac, Michigan, where we are investing approximately $4.4 million across seven municipal facilities, including city hall and the wastewater treatment plant, with solar, battery storage, upgraded HVAC and lighting, EV charging and microgrid capabilities designed to keep essential services running during grid outages. Cadillac is paying for the project through operational savings, with no upfront taxpayer cost.
5) Virtual power plants are often described as networks of distributed energy resources that operate collectively to support the grid. How would you explain the practical operation of Budderfly's virtual power plant, and how does it differ from conventional demand response programs?
A virtual power plant is an ecosystem of distributed assets, including EVs, HVAC, refrigeration, and increasingly batteries. These assets are orchestrated together across a territory to act like a large power station. When the grid is tight, the aggregate output or load reduction is served by these devices to support reliability. Participants are paid for their contribution to the greater system need.
The line between a virtual power plant and demand response is blurrier than people think. The Department of Energy’s 2023 virtual power plant liftoff report estimated that, depending on how it is defined, 30 to 60 GW of existing U.S. VPP capacity is mainly made up of demand response programs. The practical difference is in how the resources behave. Conventional demand response usually asks a customer to curtail during a limited number of called events, frequently to assist with impending grid outages or coincident peak fees for the utility. A VPP can coordinate a mix of resources, including batteries that can discharge rather than just reduce load. It can be dispatched in a more flexible way, responding to price signals, emergency needs, and stacked revenue streams across diversified power markets.
Our VPP starts from a different place than most. First, we serve the commercial middle market, a segment that has been historically excluded from demand response programs due to the operational complexities. These sites (restaurants, fitness centers, hotels, small manufacturing) represent a significant, untapped source of load flexibility for the grid. Budderfly’s VPP is unlocking it.
Second, Budderfly’s VPP is not an add-on that we need to sell customers. Because our model is set up such that we own and operate the equipment at every site we enroll, customers do not need to do anything to participate, and very few opt out. In 2026, we had a 92% retention rate.
Budderfly’s DERMS platform links the equipment already installed at our sites into one coordinated resource that can dynamically deploy power when it’s needed. In 2025, it was named one of TIME’s Best Inventions.
6) How many commercial buildings need to participate before a virtual power plant becomes economically meaningful? What determines the scale required to compete with conventional electricity generation or grid infrastructure solutions?
There is no single number of buildings, because it depends on how much flexible capacity each building contributes and how reliably it can be dispatched.
The arithmetic is simple: flexible kilowatts per site times the number of sites gives megawatts. What those megawatts are worth depends on the capacity price in the market, the minimum size needed to participate, and what it costs to enroll and operate each site. For small commercial buildings, that last cost matters most — it’s where owning and already monitoring the equipment helps us. Today we manage more than 9,000 sites, and our ambition is to aggregate tens of thousands of them into flexible grid assets that can help address the supply and demand challenge.
Compared with a new gas plant or a grid upgrade, a VPP competes on cost per reliable kilowatt and on speed. DOE cited a May 2023 Brattle Group analysis finding that a VPP made of residential devices, including smart thermostats, water heaters, EV charging and behind-the-meter batteries, could provide peaking capacity at about 40 percent lower net cost than a utility-scale battery and about 60 percent lower than a gas peaker. But that analysis focused on homes. DOE also noted that in most jurisdictions, grid planning requirements and cost-benefit assessments undervalue VPP benefits. The case for small commercial buildings, which are larger loads that we already control, deserves its own analysis.
7) Budderfly VPP operates across four major U.S. energy markets. How do market rules, utility programs, and compensation mechanisms differ among regions? Which markets currently offer the strongest commercial opportunities for demand-side VPPs?
Our VPP operates in four major U.S. markets: California (CAISO), New England (ISO-NE), PJM, including the BGE and ComEd territories, and New York (NYISO), with additional utility programs in the Southwest Power Pool (SPP) and Western Power Pool (WPP) regions. There is no single rulebook across them, and that patchwork is a big reason small businesses rarely participate. A restaurant owner should not have to decode four sets of market compliance and operational rules, so we do that for them.
The differences show up most in how a commercial customer gets paid. In PJM, DERs can compete in the capacity auction and are paid at the clearing price. The latest auction, for 2028/2029, cleared at the cap of $325 per megawatt-day, and roughly 7 GW of demand response cleared in it. As technology advances and the tech stack deepens at a facility, systems like batteries can operate in more valuable and operationally difficult programs, such as the frequency regulation and sync reserve markets.
Each market also has its own response-time and technical requirements, including sub-second timelines, which is another access barrier for small businesses.
California does not run a central capacity auction like PJM. Instead, much of the incentive for commercial flexibility has come from state programs that pay per kilowatt-hour for reducing load during grid emergencies. We have more sites in CA programs than any other for HVAC. The CPUC’s Emergency Load Reduction Program pays nonresidential customers $2 per kWh. The Energy Commission’s Demand Side Grid Support (DSGS) program, among the largest battery-focused VPP programs in the country, was funded only through the 2026 season.
In New England, demand response participates in the regional capacity market, and utility programs such as ConnectedSolutions and Energy Storage Solutions program which pay customers for the kilowatts they curtail during peak events. SPP is still building out its rules for aggregated distributed resources, while New York has multiple highly valuable and accessible programs based on the need of the grid. A federal rule, FERC Order 2222, is meant to open all of these markets to aggregated resources, but timelines differ by region.
With DSGS funding ended, batteries in CA are largely being transferred to Resource Adequacy or other use cases, weakening the drive to deploy large-scale batteries there. They are still viable in the territory, but other areas are increasingly expanding their battery programs in a competitive market for resource attention.
As the deployment of data centers outstrips the community energy availability, we expect emerging markets to roar to life faster than they have in the past, to meet the ever increasing and urgent demand.
8) How are artificial intelligence, advanced analytics, and automated controls changing the economics of building energy management? Which capabilities are already delivering measurable value, and which remain largely experimental?
AI is going to become increasingly important to energy management in a few ways. We’re already leveraging it.
First, we’re rolling out Nexus, an ecosystem for advanced remote monitoring, diagnostics, and control across a customer’s facilities. It brings the entire energy infrastructure of a customer into a single view and uses AI to learn from a facility’s historical and live data, as well as external data such as weather, to predict future behavior. Nexus will flag patterns and anomalies, and pinpoint the likely cause in real time. Budderfly’s service team oversees these analytics, confirms the findings, and steps in when human intervention is required. Many issues can be diagnosed and resolved remotely.
When it comes to demand response and our VPP, in my experience, the AI technology implemented today only pays off when applied alongside a robust fault detection and system improvement process.
Prior to AI, most companies set their thermostats to 72°F all day, or at best set a static schedule for occupied and closed. With AI, optimization strategies can be dynamically tailored in real time to each site and accommodate a wide variety of weather, business and building types, floor plans, equipment configurations and more. AI can understand the amount of energy used to accommodate comfort while optimizing the building’s operations to achieve both bill savings in a confusing tariff-based world and demand response signals.
None of this matters, however, without a strong foundation in delivering fault detection and physical deployment of infrastructure. Many commercial buildings have broken or worn out equipment, so the other HVACs and systems have to work harder to make up for the losses. This can drain a system and increase bills substantially. When the system is efficient in the first place, and fault detection is in place along with a robust deployment of onsite remediation, AI can do its job and save more than otherwise expected.
In our model, we take on the performance risk, so we need to know in kilowatt-hours and dollars whether the savings are real and where we need to install or fix equipment to achieve the expected savings.
The savings are very promising, but as an emerging technology, the research to support it is still being built out. Schneider Electric’s recent study modeled AI-enabled HVAC controls as cutting whole-building energy use by up to about 22 percent compared with traditional controls (Building Management Systems, BMS), and adding an extra 7.2 to 12.7 percent reduction to conventional digital controls’ 9.3% to 11.8% advantage on BMS. Schneider reports that the modeling was validated against pilot deployments, but it is still a model rather than a field result, so headline numbers must be taken in that context. Additionally, Schneider’s study examined typical mid-sized commercial buildings rather than small sites like restaurants or gyms.
In another recent study from MIT, they observed an average of 40% savings from AI-based optimization. This study, however, also looked at large buildings, not small commercial. As we at Budderfly, and VPP operators everywhere, apply AI optimization to more sites (and more kinds of sites) we’ll be able to learn more and keep improving on outcomes.
Latest News